Large Electrical Project Insurance
9:00am - 5:00pm Mon-Fri
We'll Reply in 15min*
Large-scale
electrical work on commercial and industrial sites carries risks that standard insurance programs weren't designed to handle. A single arc flash event on a
data center build can cause millions in
property damage, and the
rising frequency of fire and business interruption losses on data center projects is sharpening insurer scrutiny across the board. Wrap-up insurance programs, whether owner-controlled or contractor-controlled, promise to consolidate coverage for every party on a job. But the promise often falls short for electrical subcontractors who face unique exposures. Gaps in wrap-up coverage on major electrical projects can leave your firm holding six- or seven-figure liabilities that you assumed were someone else's problem. Understanding where those gaps hide, and how to close them, is the difference between a profitable project and a devastating claim.
Understanding Wrap-Up Insurance in Electrical Contracting
Wrap-up insurance programs bundle general liability, workers' compensation, and sometimes excess liability into a single policy that covers all enrolled parties on a construction project. The project owner or general contractor purchases the program, and subcontractors are enrolled as additional insureds. For electrical contractors, enrollment typically means you're asked to remove your own GL and workers' comp costs from your bid, since the wrap-up is supposed to replace them.
The appeal is real: lower overall premiums, consistent coverage terms, and centralized claims management. But wrap-ups are designed for the project as a whole, not for the specific risk profile of an electrical subcontractor pulling high-voltage cable through a 500,000-square-foot facility.
The Difference Between OCIP and CCIP
An OCIP (Owner-Controlled Insurance Program) is purchased and administered by the project owner. A CCIP (Contractor-Controlled Insurance Program) is purchased by the general contractor. The distinction matters because it determines who controls claims handling, who selects the insurer, and whose interests take priority when coverage disputes arise. Texas subcontractors, for example, face specific enrollment and compliance requirements under both OCIP and CCIP structures that vary by state regulation.
Under an OCIP, the owner's risk manager typically negotiates terms that protect the owner's balance sheet first. Under a CCIP, the GC has more control, which can be better or worse for electrical subs depending on the relationship. Either way, you're relying on someone else's insurance decisions to protect your company.
Why Electrical Projects Require Specialized Oversight
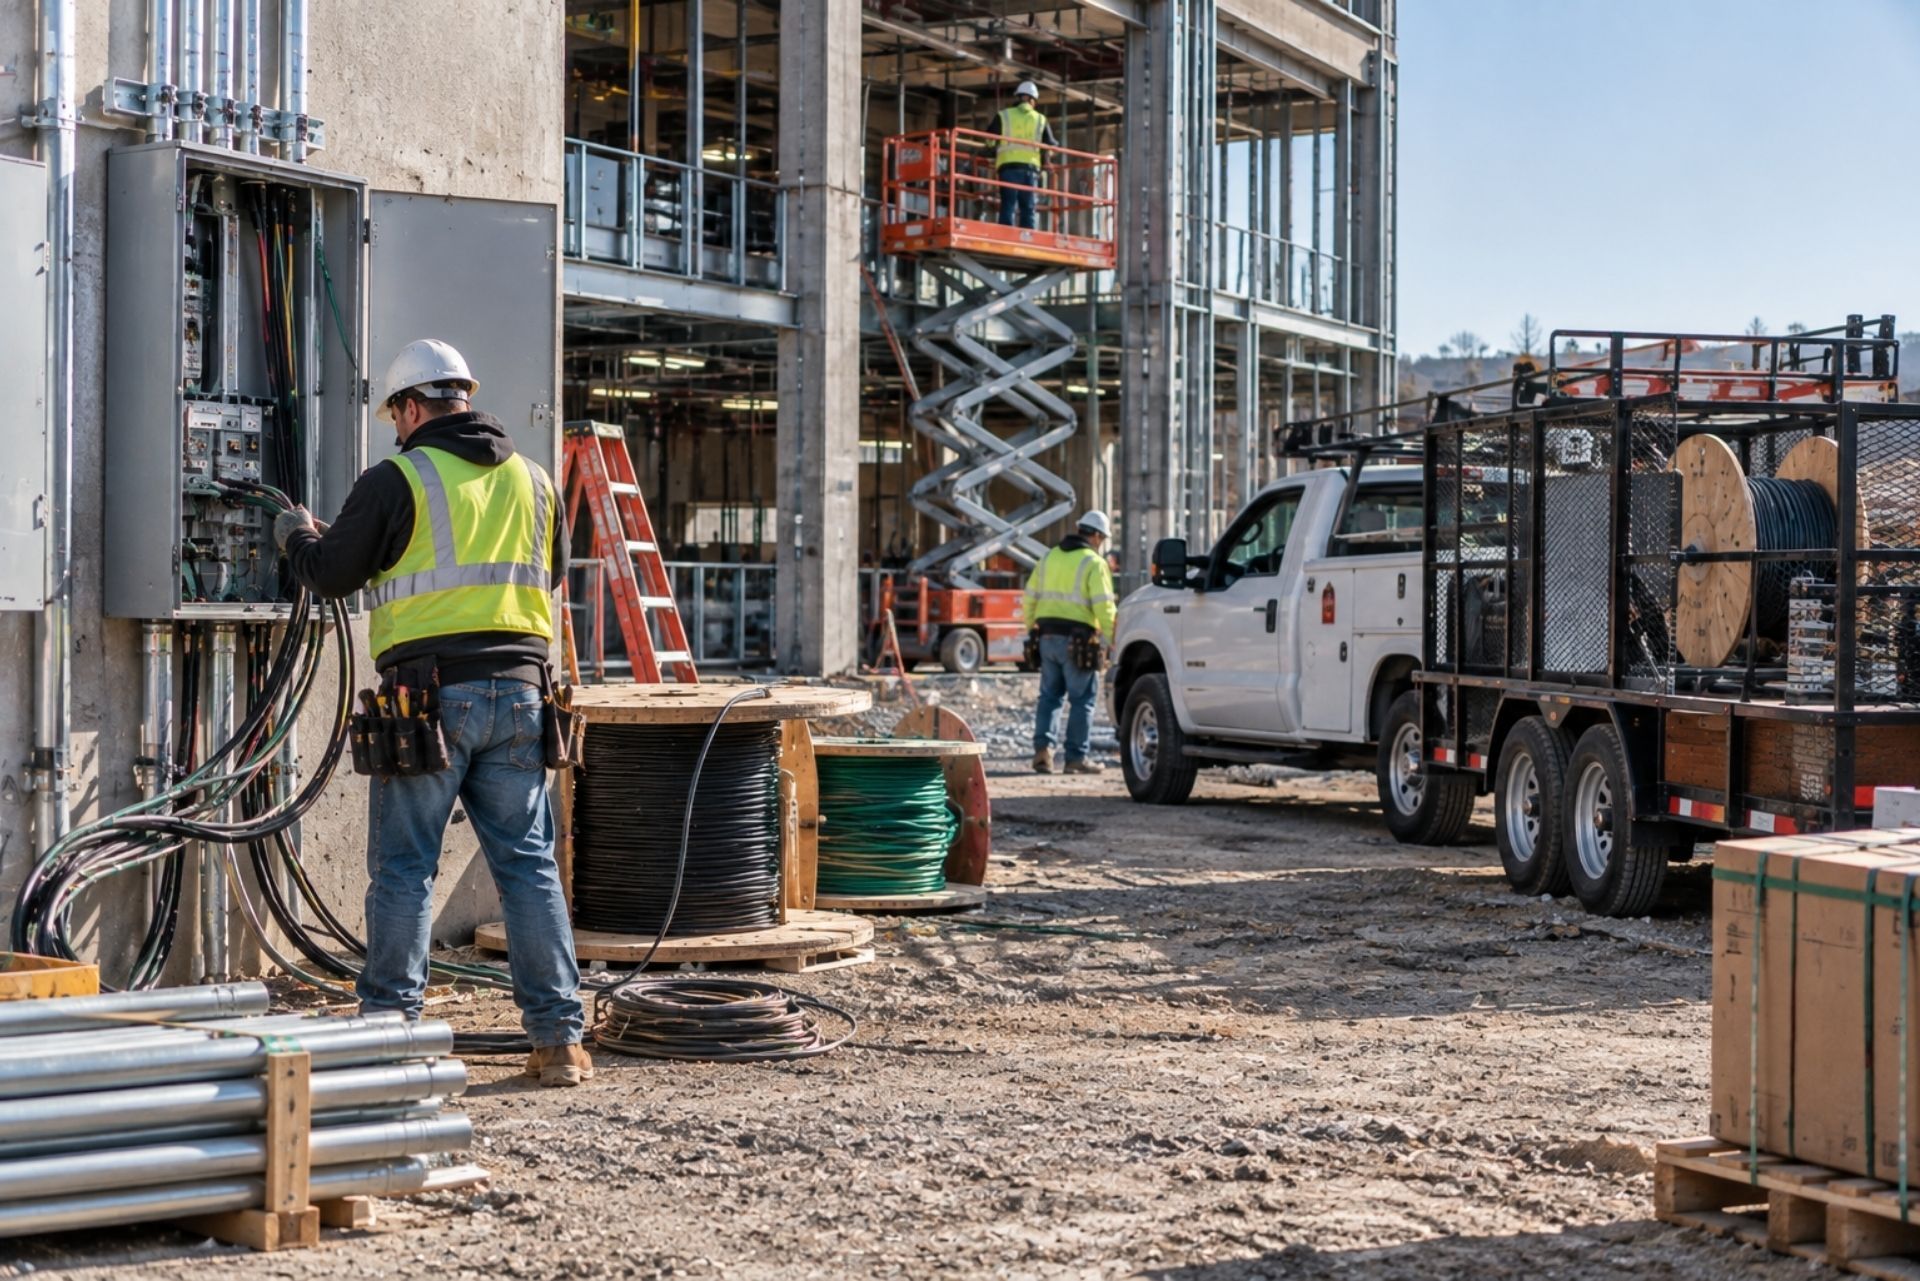
Electrical work introduces exposures that don't exist for concrete or steel trades. Arc flash injuries can be catastrophic. Faulty wiring in a completed building can cause fires years after substantial completion. Design-build electrical contracts blur the line between professional services and construction, creating liability questions that generic wrap-up policies aren't structured to answer. Your risk profile as an electrical contractor is fundamentally different from a framing crew's, and the wrap-up often treats you the same.
By: Aaron McElwain
President of Bellwether Insurance
Common Coverage Gaps for Electrical Subcontractors
Even well-structured wrap-up programs leave holes that electrical contractors fall through. These aren't theoretical risks; they're the gaps we see trigger real claims on real projects.
Off-Site Risks and Prefabrication Work
Most wrap-up policies only cover work performed at the designated project site. If your crew prefabricates electrical panels, switchgear assemblies, or conduit runs at your shop or a separate facility, that work isn't covered. A fire at your prefabrication shop that destroys $200,000 in materials destined for the project? That's on your own property and inland marine policies, not the wrap-up. The same applies to transit: materials damaged in shipping between your shop and the job site typically fall outside wrap-up coverage.
Professional Liability and Design-Build Errors
This is one of the most dangerous gaps for electrical contractors. Wrap-up programs almost never include professional liability coverage. If you're performing design-build work, providing engineering calculations, or specifying equipment, any error in those professional services is excluded from the wrap-up GL policy. Professional liability insurance for mid-market firms carrying $5M to $10M in limits costs between $5,000 and $75,000 annually, and many electrical contractors skip it entirely because they assume the wrap-up has them covered. It doesn't.
The professional liability gap is one that many project owners don't recognize until a claim surfaces, and by then the finger-pointing between insurers has already begun.
Completed Operations and Extended Reporting Periods
Wrap-up policies typically include a completed operations tail, often three to ten years after project completion. But electrical defects can manifest well beyond that window. A miswired fire alarm system that fails during an actual emergency five years post-completion could trigger a claim. If the wrap-up's completed operations period has expired, and you've let your own GL lapse or changed carriers, you may have no coverage at all. Pay close attention to the tail period and confirm it in writing before you sign enrollment documents.
Comparing Wrap-Up Coverage vs. Individual Policies
Understanding what the wrap-up actually replaces, and what it doesn't, is critical for budgeting and risk management. Here's a direct comparison:
| Coverage Area | Wrap-Up Program | Your Individual Policy |
|---|---|---|
| General Liability (on-site) | Covered | Excluded from bid; you deduct premium |
| Workers' Comp (on-site) | Covered | Excluded from bid; you deduct premium |
| Professional Liability | Not covered | Must maintain separately |
| Off-Site / Prefab Work | Not covered | Covered under your own GL |
| Tools & Equipment | Rarely covered | Covered under inland marine |
| Auto Liability | Not covered | Must maintain separately |
| Completed Operations (post-tail) | Expires after tail period | Covered if policy is active |
| Pollution Liability | Rarely covered | Must purchase separately |
The table makes one thing clear: a wrap-up is not a replacement for your own insurance program. It supplements it for on-site work during the project period. Everything else remains your responsibility.
How Insurance Gaps Create Real Financial Exposure
The widening gap between property insurance and casualty rates for U.S. construction firms means that uncovered claims hit harder than ever. A single professional liability claim on a data center electrical system can exceed $2M before attorneys' fees. An uncovered workers' comp claim for an off-site injury could cost your firm its experience modification rate for three years, driving up premiums across every project you bid.
The financial exposure isn't limited to the claim itself. Uninsured losses can trigger breach-of-contract claims from the GC, damage your
bonding capacity, and disqualify you from future wrap-up enrollment. One gap, one claim, and the ripple effects can reshape your business for years.
Managing the 'Difference in Conditions' (DIC) Strategy
A DIC policy is designed to sit alongside the wrap-up and fill the specific gaps it leaves. Think of it as a patch kit for your coverage. A well-structured DIC policy will pick up exposures that the wrap-up excludes, including off-site work, broader pollution coverage, and sometimes even professional liability.
The cost of a DIC policy varies based on your scope of work and the wrap-up's specific exclusions. Your broker should request a copy of the wrap-up policy, not just the enrollment summary, and compare it line by line against your own coverage to identify where the DIC needs to respond.
Filling Gaps with Excess Liability
Excess liability, sometimes called umbrella coverage, can extend the limits of the wrap-up or your own underlying policies. On large electrical projects where contract values run into eight figures, the wrap-up's per-occurrence limits may not be sufficient for a catastrophic loss. An excess policy that drops down to fill gaps when the wrap-up's limits are exhausted provides a critical safety net. Make sure your excess carrier is aware of the wrap-up structure so there's no dispute about priority of coverage.
Protecting Tools and Equipment Not Covered by the Wrap
Your wire pullers, conduit benders, testing equipment, and specialty tools represent a significant capital investment. Wrap-up programs don't cover contractor-owned tools and equipment. An inland marine or contractor's equipment policy is essential, and it should be reviewed annually to reflect current replacement costs. A 2024-era policy with $150,000 in scheduled equipment may be woefully inadequate if you've added $80,000 in testing gear since then.
Common Questions About Electrical Wrap-Ups
Does the wrap-up cover my employees commuting to the job site? No. Workers' compensation under a wrap-up typically begins when your employee enters the designated project site. Injuries during commute or at your office are covered by your own workers' comp policy.
Can I opt out of a wrap-up program? Generally, no. If the project requires enrollment, participation is mandatory. You may maintain your own policies in parallel, but you're still required to enroll and comply with the wrap-up's reporting requirements.
What happens if I'm working on multiple projects, some with wrap-ups and some without? You need to maintain your own GL and workers' comp for non-wrap-up projects. Your broker should structure your policies so that wrap-up projects are excluded from your own coverage to avoid double-premium charges.
Who handles claims under a wrap-up? The wrap-up administrator, not your own insurer. This means you have less control over the claims process, settlement decisions, and defense counsel selection.
Does the wrap-up cover warranty work after the project is complete? It depends on the tail period. Most wrap-ups include a completed operations extension, but warranty callbacks that occur after the tail expires fall back on your own GL policy.
What 2026 Construction Trends Mean for Electrical Wrap-Ups
The construction insurance market in 2026 is shifting in ways that directly affect electrical contractors on wrap-up projects. Data center construction continues to accelerate, and fires on these projects are increasing risk for insurers who underwrite wrap-up programs. That increased risk translates to tighter underwriting, higher deductibles, and more exclusions in wrap-up policies.
The five key numbers shaping construction industry trends in 2026 point to rising project values and longer construction timelines, both of which increase the duration and magnitude of your exposure under a wrap-up. Electrical contractors bidding on projects with 24- to 36-month timelines need to confirm that the wrap-up's policy period matches the actual construction schedule, including any anticipated delays.
Steps to Audit Your Wrap-Up Enrollment
Before you sign enrollment documents, take these steps:
- Request the full wrap-up policy, not just the summary or certificate of insurance.
- Compare the wrap-up's exclusions against your own coverage to identify gaps.
- Confirm the completed operations tail period and its expiration date.
- Verify that off-site and prefabrication work is either covered or addressed by your own policies.
- Ask whether professional liability is included. If it isn't, confirm your own PL policy is active and adequate.
- Review the wrap-up's per-occurrence and aggregate limits against your contract value.
- Document everything in writing with your broker and the wrap-up administrator.
Negotiation Tactics for Subcontractors
You have more negotiating power than you think. Before enrollment, ask the GC or owner for a copy of the wrap-up's loss runs from prior projects. High loss ratios suggest the program may face mid-project premium adjustments that could affect your deductible obligations.
Negotiate for a named-insured status rather than just additional-insured status where possible. Push for written confirmation that the wrap-up's defense obligations extend to your firm independently, not just as part of the project's collective defense. If the wrap-up excludes pollution liability and your scope includes work near transformers or battery storage systems, insist on a carve-out or obtain standalone pollution coverage.
The Bottom Line for Electrical Contractors
Wrap-up insurance programs on large electrical projects offer genuine benefits: consolidated coverage, lower bid costs, and centralized claims management. But they're not a complete safety net for your firm. The gaps in professional liability, off-site work, tools and equipment, and post-completion exposure are real, and they're your responsibility to close.
Every wrap-up enrollment should trigger a coverage audit with your broker. Compare the wrap-up's terms against your existing program, identify the gaps, and fill them with DIC policies, excess liability, or standalone coverage before your crew sets foot on the job site. The cost of closing these gaps is a fraction of what an uncovered claim will cost you.
Don't assume the wrap-up has you covered. Read the policy, ask hard questions, and protect your business with the same precision you bring to your electrical work.
About The Author:
Aaron McElwain, CIC
As President of Bellwether Insurance, I’m passionate about helping individuals and businesses protect what matters most through honest advice and reliable coverage. With my Certified Insurance Counselor (CIC) designation and years of industry experience, I focus on simplifying insurance, building lasting relationships, and delivering peace of mind through every policy we write.
OUR PERSONAL INSURANCE COVERAGE IN OHIO
Explore Personal Insurance Coverage in Ohio
We only work with outstanding insurance companies that offer great value and continually impress our clients.
Home Insurance
Protecting Ohio homes, ensuring comfort
Life Insurance
Safeguard futures, cherish moments
Umbrella Insurance
Extra coverage, ultimate peace
Car Insurance
On the road, confidently insured
Condo & Renters Insurance
Customized policies, worry-free living
Motorcycle Insurance
Ride fearlessly, enjoy the journey
Choose Bellwether Insurance Today for Personalized Protection
Get a Plan Tailored to Your Lifestyle
Bellwether Insurance evaluates the risks you and your family face, taking into account your assets, personal circumstances, and individual requirements to create a tailored insurance solution.
Recover with Confidence
With our personal insurance coverage, you'll be prepared to bounce back from unforeseen events that could have left you and your family in a difficult financial situation.
Avoid Overpaying
Through customized insurance plans, you'll receive adequate coverage without unnecessary costs. At Bellwether Insurance, we strive to keep premiums cost-effective while providing the protection you need.
Review from our Clients
Customer Testimonials
See why Ohio residents work with Bellwether Insurance Agency in LaGrange, Ohio


Arun K.
Personal Insurance Client
After a decade old relationship with a premium and commercial insurance provider.. my switch to Bellwether has left me wondering why I waited so long. Primarily my experience has been dealing with Jessica Fox.. and she's been awesome to work with. She's super responsive, stays on top to follow up on your enquiries and really gets things done to delight customers.

Rob J.
Personal Insurance Client
Absolute pleasure to work with. Sandra has taken care of all my insurance needs for over 2 years now. Bellwether was able to save me quite a bit of money over previous carrier. Always giving heads up on any changes, or weather it’s time to check for new price she’s on top of it. I recommend them often to friends and family.

Nick W.
Personal Insurance Client
Aaron and Sandra are amazing! I faithfully stayed with my previous insurance for over ten years until I had them review my policies. Wish I would have done it years ago. Saved me quite a bit of money as well as gaining coverage what's not to love? They respond very quickly and professionally. I work in sales as a profession so it's great to see that level of attention and attentiveness provided here. Stop your search and give them a shot you won't regret it. On a side note even though it is something so small I love the fact they send laminated copies of insurance cards anytime you make a change. 10/10

Bobby P.
Personal Insurance Client
Bellwether Insurance is the best ever! Always there when I need them and always has the answers with quick replies. I will never go with a different Insurance Agent. If I could, I would give then a 10 Star review! Thanks Sandra for all your help!