Ohio Boiler E&O Insurance
9:00am - 5:00pm Mon-Fri
We'll Reply in 15min*
A single missed inspection step or an overlooked maintenance item on a commercial boiler can spiral into a six-figure claim before you've even had time to review the service contract. For boiler professionals operating in Ohio, the stakes are particularly high: updated state administrative codes, harsh seasonal demands on heating equipment, and a growing shortage of qualified technicians all increase the odds that something goes wrong and someone points a finger at your business. E&O insurance for boiler service contract claims in Ohio isn't a luxury or a box to check - it's a financial lifeline that determines whether your company survives a professional negligence allegation or closes its doors.
Ohio's regulatory environment for boiler inspection and maintenance has shifted meaningfully in 2026, and the gap between what general liability covers and what you actually need has widened. If you inspect, maintain, design, or service commercial or industrial boilers, understanding
professional liability protection is no longer optional. This guide breaks down inspection errors, missed maintenance claims, equipment failure disputes, contract disagreements, and the defense strategies that keep Ohio boiler service companies solvent.
Understanding Errors and Omissions for Ohio Boiler Professionals
Errors and omissions insurance, often shortened to E&O, is a form of professional liability coverage designed to protect service providers against claims arising from their professional advice, work product, or failure to perform contracted duties. For boiler technicians and HVAC contractors, this means coverage when a client alleges that your inspection missed a critical defect, your maintenance schedule was inadequate, or your recommendations led to equipment failure.
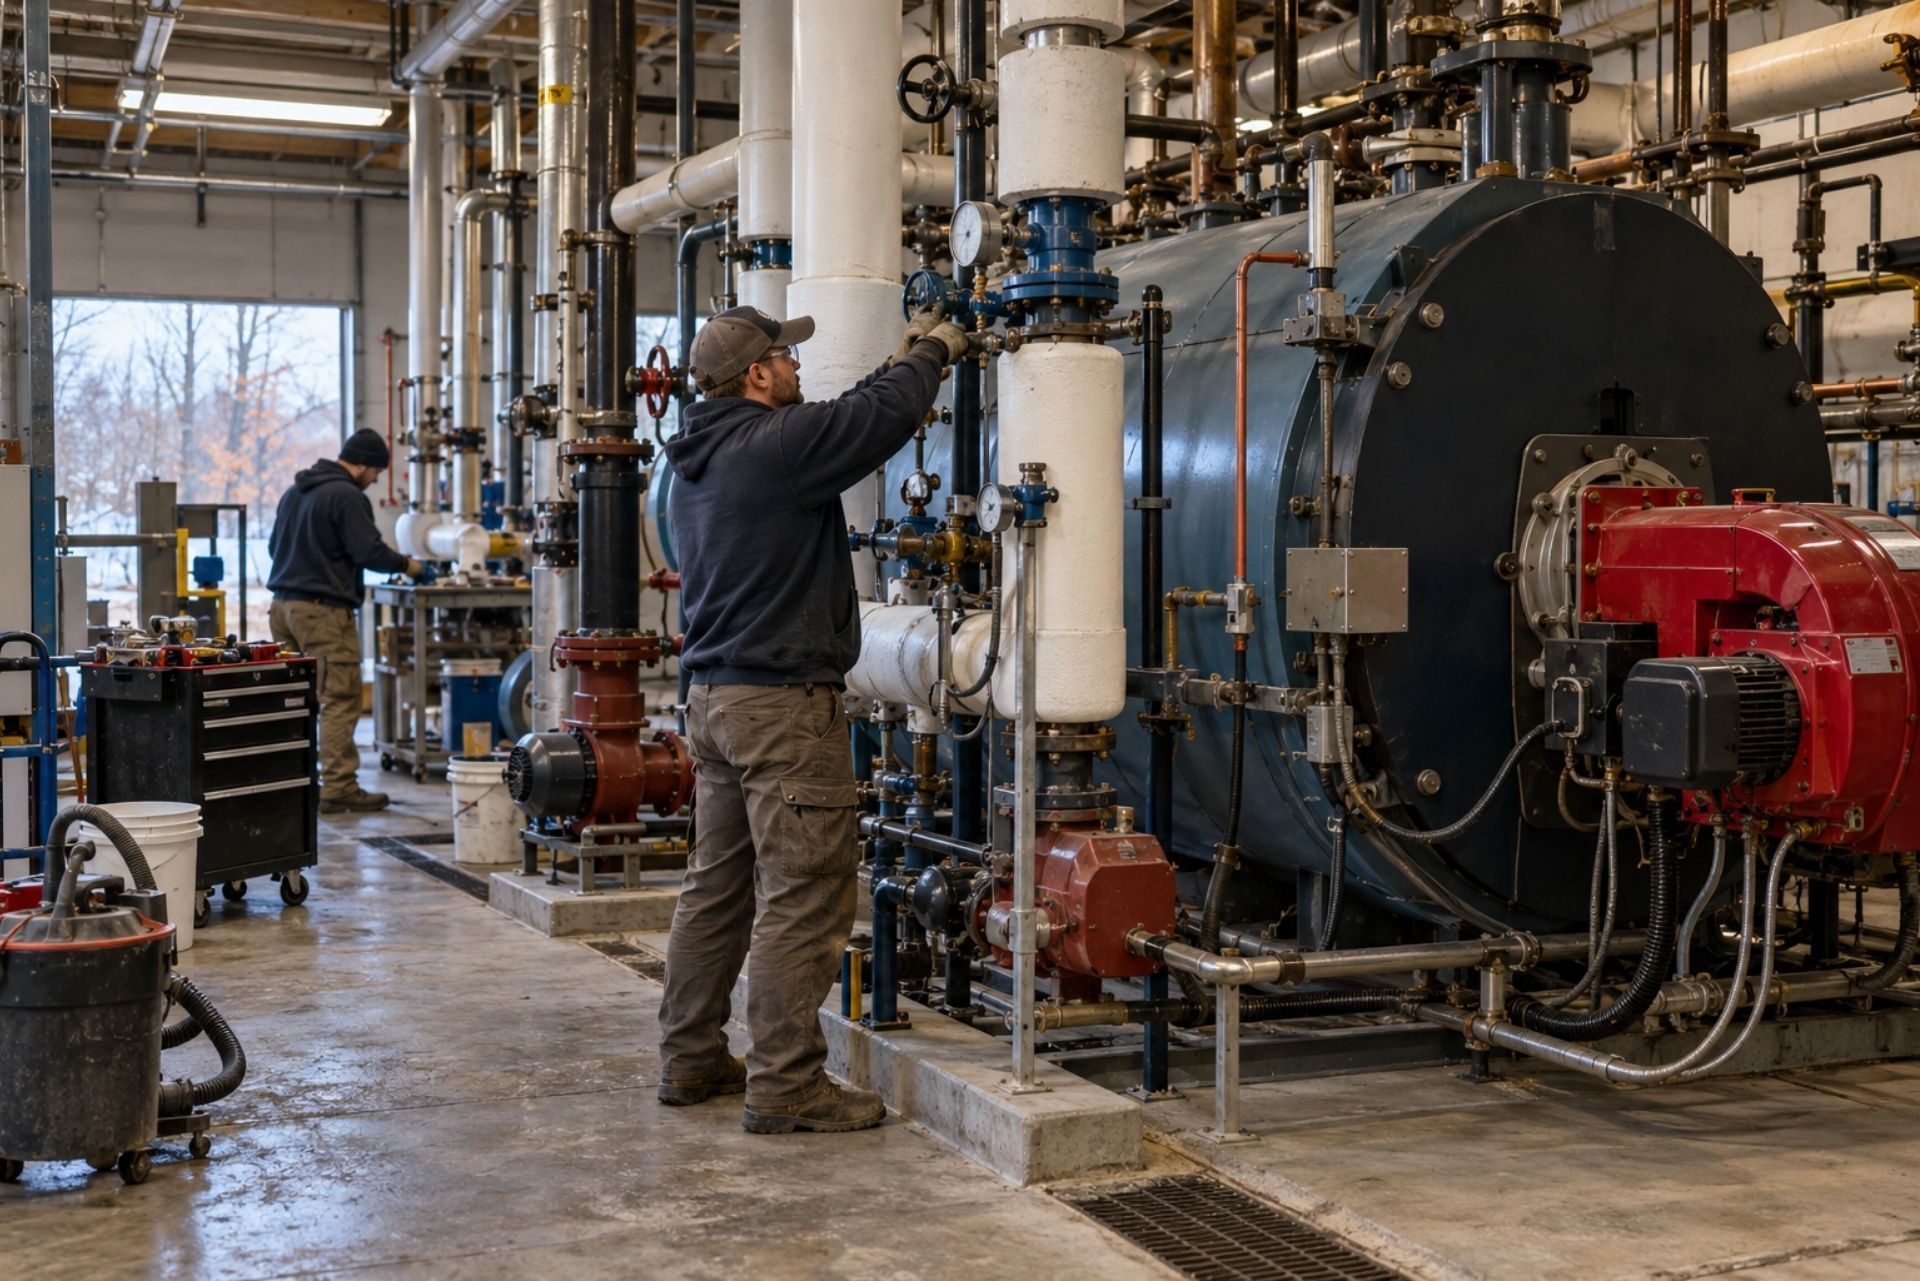
The distinction matters because boiler work is inherently technical and high-consequence. A residential furnace repair gone wrong might cost a few thousand dollars. A commercial boiler failure tied to a missed inspection can cause property damage in the hundreds of thousands, business interruption losses, and even personal injury claims. E&O coverage addresses the professional judgment component of these situations, covering your defense costs and any resulting settlements or judgments.
Why Standard General Liability Isn't Enough
General liability insurance covers bodily injury and property damage caused by your business operations, like a technician accidentally damaging a client's wall during a service call. It does not cover claims that arise from your professional expertise or lack thereof. If a building owner sues you because your inspection report failed to identify a corroded pressure vessel, that's a professional liability claim, and your general liability policy will almost certainly exclude it.
This gap catches many Ohio boiler contractors off guard. They carry general liability, workers' compensation, and perhaps commercial auto coverage, then assume they're fully protected. The first time a client alleges negligent inspection or inadequate maintenance recommendations, they discover the gap the hard way. Ohio law already requires licensed insurance producers to carry E&O coverage as a condition of licensure, reflecting the state's recognition that professional liability risks demand dedicated protection.
Common E&O Triggers in HVAC and Boiler Servicing
The most frequent claims against boiler service professionals fall into predictable categories:
- Inspection errors: Failing to identify cracks, corrosion, or pressure relief valve malfunctions during a scheduled inspection
- Missed maintenance items: Skipping water treatment checks, neglecting tube cleaning schedules, or overlooking combustion efficiency testing
- Faulty recommendations: Advising a client that equipment is safe to operate when it isn't, or recommending repairs that prove insufficient
- Documentation failures: Incomplete service records that leave you unable to prove what work was performed
- Contract scope disputes: A client believes your service agreement covered a component that you considered outside scope
Each of these triggers can generate a claim regardless of whether you actually made an error. The allegation alone is enough to require a legal defense, which is where E&O coverage pays for itself.
By: Aaron McElwain
President of Bellwether Insurance
Comparison: General Liability vs. Professional Liability (E&O)
Understanding the practical differences between these two policy types helps you identify where your current coverage falls short. Many boiler contractors carry one but not the other, leaving a significant exposure.
Coverage Comparison Table
| Feature | General Liability (GL) | Professional Liability (E&O) |
|---|---|---|
| Bodily injury from operations | Covered | Not covered |
| Property damage from operations | Covered | Not covered |
| Negligent inspection claims | Not covered | Covered |
| Missed maintenance allegations | Not covered | Covered |
| Faulty professional advice | Not covered | Covered |
| Contract dispute defense | Rarely covered | Typically covered |
| Legal defense costs | Included (within limits) | Included (within limits) |
| Claims-made vs. occurrence | Usually occurrence | Usually claims-made |
| Typical annual premium range | Varies by payroll/revenue | Varies by service volume and risk |
One critical difference: most E&O policies operate on a claims-made basis, meaning they cover claims filed during the active policy period regardless of when the alleged error occurred, as long as it happened after the retroactive date. If you let your E&O policy lapse, you lose protection for past work. This is why tail coverage matters if you ever change carriers or close your business.
Ohio presents a unique combination of regulatory requirements, weather patterns, and workforce challenges that shape the risk profile of boiler service professionals. Understanding these factors helps you anticipate where claims are most likely to originate.
State Licensing and Inspection Standards
Ohio's boiler regulations are administered under the Ohio Administrative Code Chapter 1301:3-5, and they've seen meaningful updates in 2026. The updated rules under OAC 1301:3-5-02, effective January 1, 2026, now mandate specific preparation steps for internal boiler inspections, including cooling, cleaning, and removing all manhole and handhole plates before inspection begins. Failure to follow these preparation requirements can expose your company to claims if a subsequent failure is traced back to an incomplete inspection.
Ohio has also updated its fee schedule for boiler certificates of operation effective January 5, 2026, covering both annual renewals and triennial inspections. These fees and requirements are governed under Ohio Administrative Code Chapter 1301:3-5. Staying current with these changes isn't just a compliance issue; it's a liability issue. If you're unaware of updated inspection preparation standards and a client's boiler fails after your service, the claim against you becomes much harder to defend.
Impact of Extreme Ohio Weather on System Failure Claims
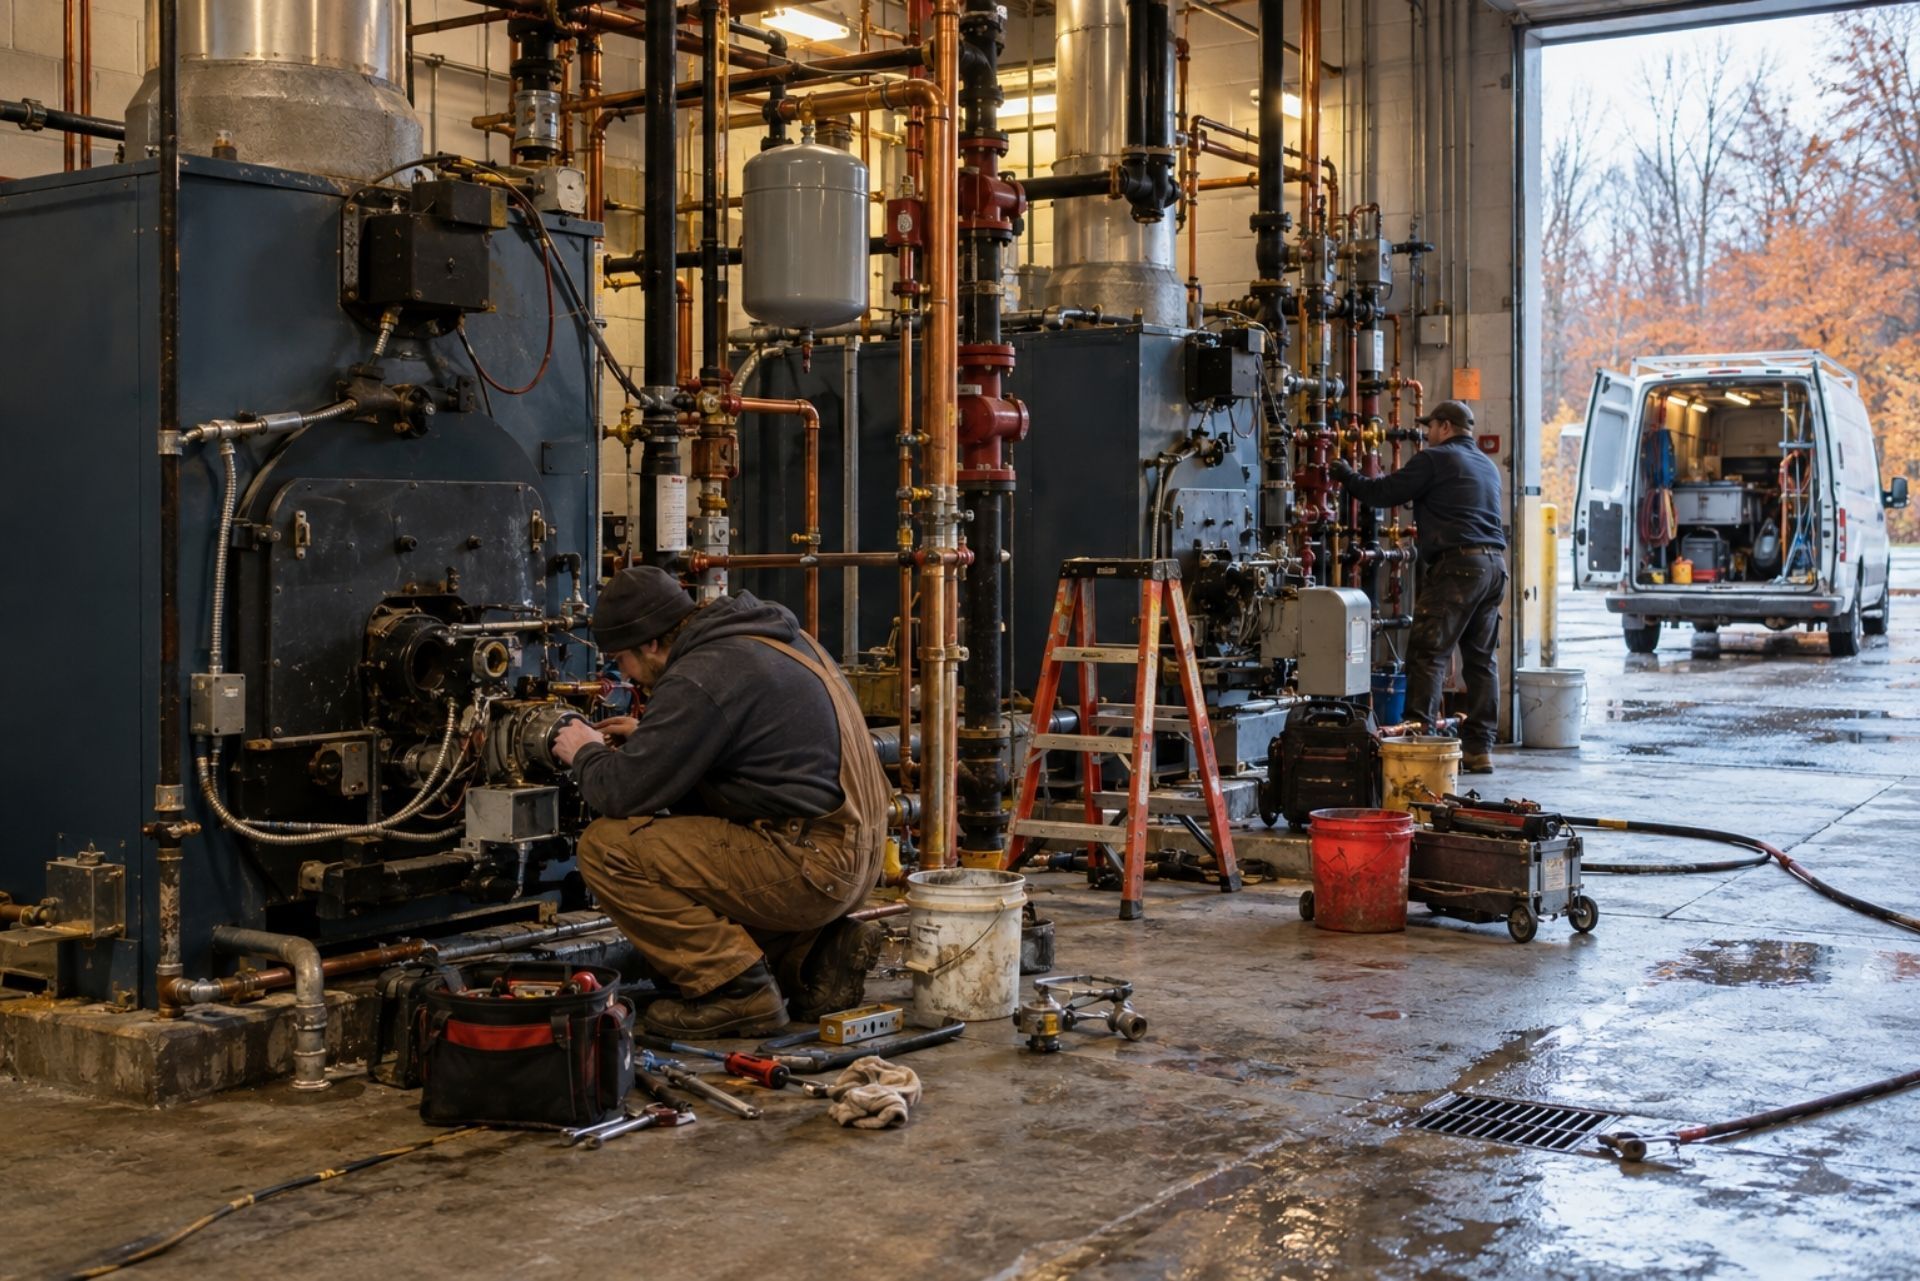
Ohio's climate puts extraordinary stress on boiler systems. Winter temperatures that drop well below freezing for extended periods push heating equipment to its operational limits. Freeze-thaw cycles accelerate corrosion in older systems. Spring flooding can damage below-grade boiler rooms in ways that aren't immediately visible.
These conditions create a predictable spike in equipment failure claims every heating season. When a commercial boiler fails during a January cold snap, the building owner's first question is whether the service contractor missed something during the fall inspection. Even if the failure was caused by age or a manufacturing defect, your company will likely be named in the claim. E&O coverage for boiler professionals operating in Ohio must account for this seasonal risk pattern.
The workforce shortage compounds the problem. McKinsey estimates there will be 20 skilled trade openings for every one new worker through 2032, which means boiler service companies are often stretched thin during peak demand. Overworked technicians are more likely to make errors, and understaffed companies may cut corners on documentation. Both scenarios increase E&O exposure.
Key Components of a Robust Boiler E&O Policy
Not all E&O policies are created equal. A policy designed for general contractors won't address the specific risks that boiler inspection and maintenance professionals face. Here's what to look for when evaluating coverage.
Faulty Design and Installation Coverage
If your company handles boiler system design, installation, or modification in addition to inspection and maintenance, your E&O policy needs to explicitly cover design and installation errors. Some policies limit coverage to inspection and advisory services only. A boiler that was improperly sized for the building's heating load, or installed with incorrect piping configurations, generates a different type of claim than a missed inspection item, and your policy language needs to address both.
Look for policy language that covers "professional services" broadly rather than listing specific activities. The broader the definition, the less likely you are to encounter a coverage gap when a claim arrives. Pay attention to exclusions as well: some policies exclude claims related to pollution, mold, or asbestos, all of which can arise in older boiler installations.
Legal Defense Costs and Settlement Protection
Defense costs are often the most expensive part of an E&O claim, even when you've done nothing wrong. Attorney fees, expert witness costs, document production, and deposition preparation can be significant, as a single expert witness engagement for a mechanical failure case can range from $2,500 to over $25,000 (https://expertslate.com/blog/how-much-does-expert-witness-cost/). Your policy should cover these costs either within the policy limits or, preferably, in addition to the policy limits.
Settlement protection is equally important. Many E&O policies include a "consent to settle" clause that prevents the insurer from settling a claim without your agreement. This matters because a settlement can affect your professional reputation and future insurability. On the other hand, some policies include a "hammer clause" that penalizes you financially if you refuse a settlement the insurer recommends. Read these provisions carefully before you buy.
Frequently Asked Questions About Boiler Insurance
Do I need E&O insurance if I only perform boiler inspections, not repairs? Yes. Inspection-only work carries significant professional liability exposure. If your inspection report misses a defect that later causes a failure, you'll face a negligence claim regardless of whether you performed any physical repairs.
What's the difference between claims-made and occurrence-based E&O policies? Claims-made policies cover claims filed during the active policy period. Occurrence policies cover incidents that happen during the policy period, even if the claim is filed years later. Most boiler E&O policies are claims-made, which means maintaining continuous coverage is critical.
How much E&O coverage does a typical Ohio boiler service company need? Coverage needs depend on your contract values, client types, and risk tolerance. Commercial boiler contractors serving large facilities often carry $1 million to $2 million in E&O limits, but your specific situation may require more or less.
Will my E&O policy cover a dispute over the scope of my service contract? Most E&O policies cover defense costs for contract disputes related to your professional services. If a client claims your service agreement included work you didn't perform, the policy should respond. Review your policy's definition of "wrongful act" to confirm.
Does E&O insurance cover equipment I damage during a service call? No. Physical damage you cause to a client's property during service is a general liability claim. E&O covers claims arising from your professional judgment, advice, or failure to perform professional duties.
Can I get E&O coverage if I've had a prior claim?
Yes, though your premiums will likely be higher. Insurers will want details about the prior claim, its resolution, and what steps you've taken to prevent similar issues. A well-documented risk management program helps.
Making the Right Choice for Your Service Business
Choosing the right E&O protection for your Ohio boiler service company comes down to matching your actual risk profile with appropriate coverage. Start by cataloging every professional service you offer: inspection, maintenance, design, installation, consulting, emergency repair. Then verify that your policy's definition of covered professional services includes each one.
Review your service contracts for indemnification clauses, limitation of liability provisions, and scope definitions. These contract terms interact directly with your E&O coverage. A poorly drafted service contract can create liability that your E&O policy won't cover, or it can include indemnification obligations that exceed your policy limits.
Don't overlook the importance of documentation. The single most effective defense against a boiler service E&O claim is thorough, contemporaneous documentation of every inspection, every maintenance task, every recommendation, and every client communication. When a claim arrives two years after a service call, your records are your primary defense.
Ohio's updated boiler inspection standards, seasonal equipment stress, and the ongoing skilled labor shortage all point in the same direction: professional liability exposure for boiler service companies is increasing. The right E&O policy, paired with strong contracts and disciplined documentation, gives your business the foundation to handle claims without catastrophic financial consequences. Talk to a broker who understands both professional liability and the boiler service industry before your next policy renewal.
About The Author:
Aaron McElwain, CIC
As President of Bellwether Insurance, I’m passionate about helping individuals and businesses protect what matters most through honest advice and reliable coverage. With my Certified Insurance Counselor (CIC) designation and years of industry experience, I focus on simplifying insurance, building lasting relationships, and delivering peace of mind through every policy we write.
OUR PERSONAL INSURANCE COVERAGE IN OHIO
Explore Personal Insurance Coverage in Ohio
We only work with outstanding insurance companies that offer great value and continually impress our clients.
Home Insurance
Protecting Ohio homes, ensuring comfort
Life Insurance
Safeguard futures, cherish moments
Umbrella Insurance
Extra coverage, ultimate peace
Car Insurance
On the road, confidently insured
Condo & Renters Insurance
Customized policies, worry-free living
Motorcycle Insurance
Ride fearlessly, enjoy the journey
Choose Bellwether Insurance Today for Personalized Protection
Get a Plan Tailored to Your Lifestyle
Bellwether Insurance evaluates the risks you and your family face, taking into account your assets, personal circumstances, and individual requirements to create a tailored insurance solution.
Recover with Confidence
With our personal insurance coverage, you'll be prepared to bounce back from unforeseen events that could have left you and your family in a difficult financial situation.
Avoid Overpaying
Through customized insurance plans, you'll receive adequate coverage without unnecessary costs. At Bellwether Insurance, we strive to keep premiums cost-effective while providing the protection you need.
Review from our Clients
Customer Testimonials
See why Ohio residents work with Bellwether Insurance Agency in LaGrange, Ohio


Arun K.
Personal Insurance Client
After a decade old relationship with a premium and commercial insurance provider.. my switch to Bellwether has left me wondering why I waited so long. Primarily my experience has been dealing with Jessica Fox.. and she's been awesome to work with. She's super responsive, stays on top to follow up on your enquiries and really gets things done to delight customers.

Rob J.
Personal Insurance Client
Absolute pleasure to work with. Sandra has taken care of all my insurance needs for over 2 years now. Bellwether was able to save me quite a bit of money over previous carrier. Always giving heads up on any changes, or weather it’s time to check for new price she’s on top of it. I recommend them often to friends and family.

Nick W.
Personal Insurance Client
Aaron and Sandra are amazing! I faithfully stayed with my previous insurance for over ten years until I had them review my policies. Wish I would have done it years ago. Saved me quite a bit of money as well as gaining coverage what's not to love? They respond very quickly and professionally. I work in sales as a profession so it's great to see that level of attention and attentiveness provided here. Stop your search and give them a shot you won't regret it. On a side note even though it is something so small I love the fact they send laminated copies of insurance cards anytime you make a change. 10/10

Bobby P.
Personal Insurance Client
Bellwether Insurance is the best ever! Always there when I need them and always has the answers with quick replies. I will never go with a different Insurance Agent. If I could, I would give then a 10 Star review! Thanks Sandra for all your help!